This is Archived content. Explore our latest Insights for recent updates and perspectives.
Create choice and guide the customer
The insurance industry is undergoing significant change, and we are all trying to predict where it is heading. Historically, one of the best ways to make such predictions has been to look for parallels, especially between things that seem to have little in common on the surface but reveal interesting analogies. A good example is comparing insurance with the music industry. At first glance, they have little in common, but there are some lessons insurers can learn from it.
Insurers are very much like recording studios from the 80s and 90s. Compare insurance to a recording studio such as Universal.
Music was distributed in the form of albums, and it was the studio that decided which songs went on which album. If you, as a customer, wanted to listen to a specific song, you had to buy the whole album compiled by the studio. This resembles the way insurance products are created – several risks are bundled together, and customers who need only some of them still have to buy the whole product.
Then iTunes came along – a step in the right direction.
Customers could now select and buy each song individually. iTunes resembles modern InsurTechs: straightforward products and a simple sales process, sometimes prioritised over extensive insurance know-how. But this model was not the final stage in the evolution of the music industry. One reason is known as “choice overload”.
In 2000, psychologists from Columbia and Stanford Universities published a study involving jams. On one day at a local food market, shoppers were presented with 24 different kinds of jam. On another day at the same market, they were offered only six. The first display attracted much more attention, but the second generated significantly more sales – in fact, ten times more.
Choice overload makes customers browse more but purchase less.
Too much choice can paralyse consumers. The music industry has already addressed this issue. Spotify is a good example.
Spotify not only offers individual songs but also allows users to create playlists and provides automatically recommended playlists. In fact, three different machine learning mechanisms are applied so that each Spotify user receives a personalised playlist. This model, which we could call “guided freedom of choice”, is interesting not only from a technological perspective but also because it can lead to strong business results.
For the music industry, digital distribution initially seemed like a niche, just as digital channels once did in insurance. But look at what happened.
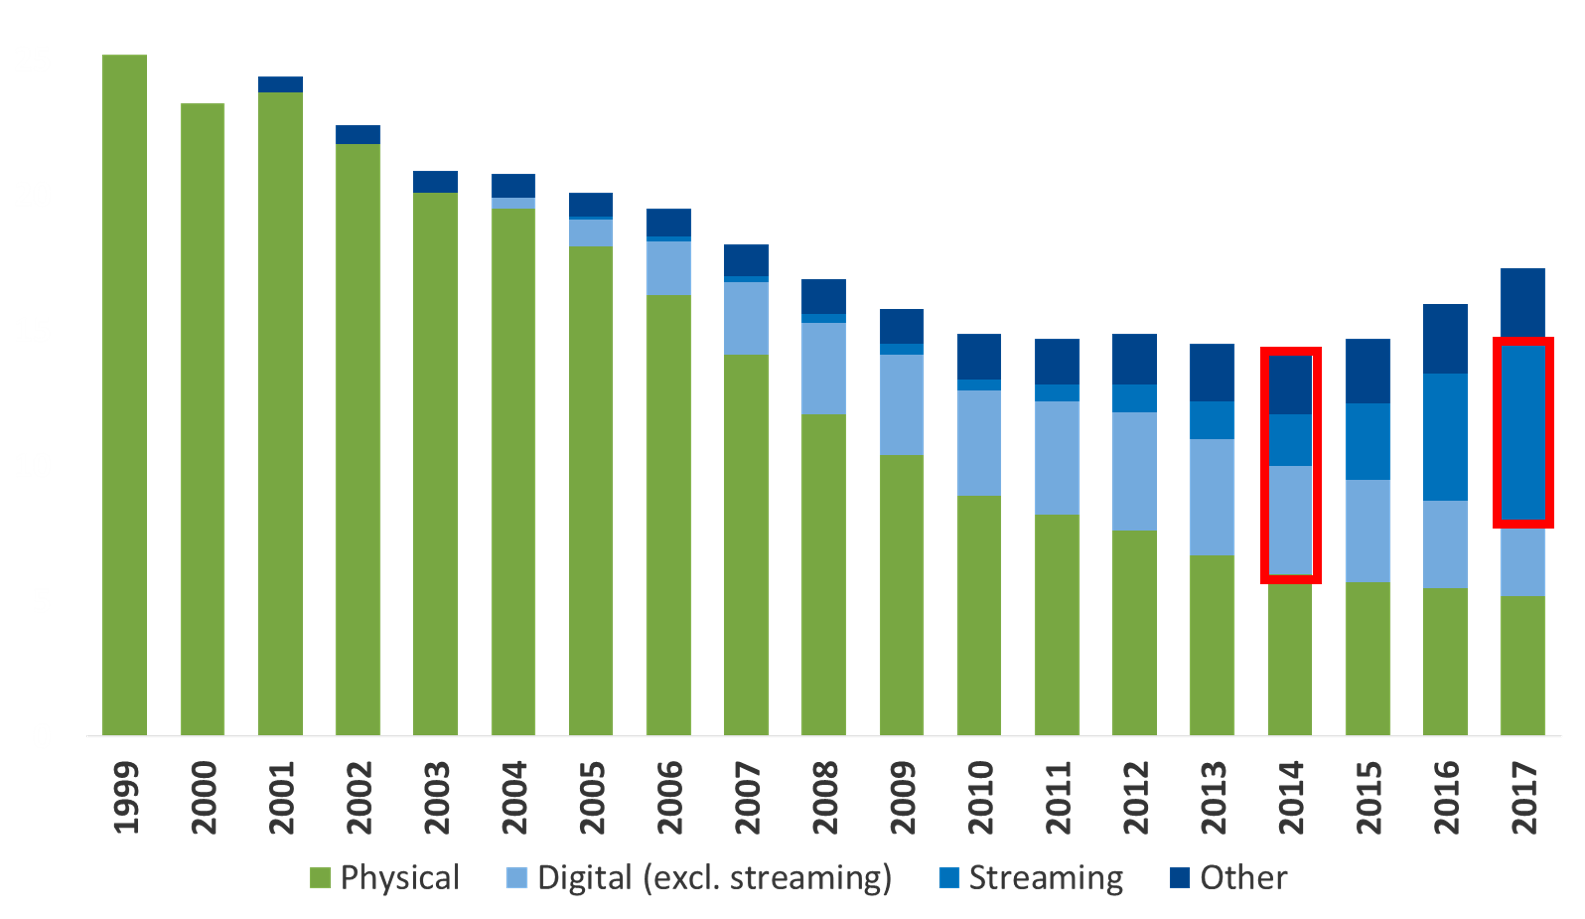
In 2014, digital distribution caught up with physical distribution, and by 2017 streaming itself had become the largest channel.
“Once these changes gained pace, they became incredibly fast.”
A similar trend is unfolding in insurance. There are, of course, many differences, most notably strict regulations, which mean that the digital revolution in our industry is progressing more slowly and will follow a different path from the journey from Universal to Spotify. Nevertheless, the direction is inevitable.
In discussions with insurers across different markets, we identified a pattern of four distinct digitalisation types. We concluded that the insurance industry should be able to serve digital customers digitally and traditional customers traditionally – according to their preferences, while preserving the underlying principles of the industry.